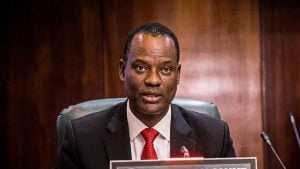
The autumn air in Abuja carried more than the usual harmattan dust when Minister of Finance and Coordinating Minister of the Economy Taiwo Oyedele stood before a modest gathering in the Federal Ministry of Finance conference room on September 17, 2026, to inaugurate the Technical Subcommittee on Fiscal Policy and Tax Reforms. Behind him hung the framed portraits of past finance chiefs, silent witnesses to decades of fiscal tinkering, while before him lay a stack of 134 stakeholder submissions that had arrived from the six geopolitical zones, each a testament to the hopes and frustrations stirred by the nation’s most ambitious tax overhaul in a generation. The four statutes that had taken effect on January 1, 2026—the Nigeria Tax Act 2025, the Nigeria Tax Administration Act 2025, the Nigeria Revenue Service (Establishment) Act 2025, and the Joint Revenue Board (Establishment) Act 2025—were meant to sweep away the labyrinthine remnants of military-era decrees and replace them with a harmonised, transparent system capable of funding the Tinubu administration’s infrastructural dreams. Yet, as Oyedele reminded his audience, the true measure of any reform lies not in the elegance of its drafting but in the messy reality of its encounter with markets, ledgers, and the everyday calculations of traders in Lagos, farmers in Kaduna, and tech startups in Enugu.
The minister’s words, “The real test begins when the law meets the economy, as businesses interpret it, administrators implement it, investors respond to it, and citizens experience it,” hung in the room like a challenge and a promise, setting the tone for a six‑week exercise that would scrutinise ambiguities, unintended consequences, and compliance burdens while seeking to preserve the reform’s core principles. With the clock ticking toward a deadline that would feed directly into the Finance Bill 2027, the subcommittee embarked on a mission that was as much about learning from implementation as it was about shaping the next chapter of Nigeria’s fiscal destiny.
The Fiscal Crucible: Ambiguities in the New Tax Architecture
In the weeks following the inauguration, the subcommittee dove into a sea of technical documents, stakeholder memos, and field reports that illuminated the friction points where the 2025 tax laws met the lived economy. According to the Politics Nigeria report, the minister had explicitly charged the panel to examine provisions that had created uncertainty or unintended effects since the framework came into force, asking where implementation had revealed ambiguity, where unintended consequences had emerged, where compliance could be simplified, and where investment and competitiveness could be improved. This directive resonated with the concerns raised earlier by the organised private sector, whose open letter to President Tinubu in June 2026 had warned that conflicting interpretations of the new tax laws had effectively paralysed corporate tax filings across the country, particularly regarding the treatment of Companies Income Tax for accounting periods that ended before January 1, 2026. The letter, signed by bodies ranging from the Manufacturers Association of Nigeria to the Nigerian Employers’ Consultative Association, argued that while the General Transition Guidelines issued by the minister’s office stipulated that pre‑commencement tax obligations should remain under the repealed statutes, the Nigeria Revenue Service’s Emerging Taxpayers Office had issued a notice directing companies to file under the new framework, a move the private sector viewed as an overreach that undermined the spirit of reform.
The subcommittee’s mandate to review the Deduction of Tax at Source Regulations 2024 and prepare revised withholding tax regulations directly addressed these grievances, aiming to align procedural guidance with legislative intent and to eliminate the costly discretion that had bred arbitrage and eroded trust. Meanwhile, the Leadership Newspaper highlighted that Value Added Tax thresholds, withholding tax, and capital gains treatment sat at the centre of the review, reflecting the 134 submissions that called for clearer rules around VAT thresholds and simpler procedures for withholding tax and capital gains, a chorus that echoed through the chambers of the Central Bank of Nigeria, the Debt Management Office, and the Joint Revenue Board, all of which were represented on the panel. By weaving together these strands—legal technicalities, private‑sector anxieties, and institutional perspectives—the subcommittee sought to map a terrain where the letter of the law could be reconciled with the spirit of economic efficiency, ensuring that the reform’s revenue‑raising goals did not become a drag on productive activity.
The Human Ledger: Stakeholder Voices from Market to Ministry
Beyond the corridors of Abuja, the review’s reach extended into the bustling markets of Onitsha, the industrial estates of Ogun, and the tech hubs of Yaba, where the human impact of tax policy is measured not in GDP points but in the ability of a trader to keep her stall open, a manufacturer to pay his workers, or a startup to attract venture capital. The Daily Trust article captured this dimension vividly, noting that the review would examine areas including Value Added Tax thresholds, withholding tax, capital gains treatment, and multiple taxation, while also considering concerns raised by the organised private sector and other stakeholders about the real‑world consequences of the new laws. In the same vein, Punch Nigeria reported that the six‑week exercise aimed to address implementation gaps, ambiguities, and unintended consequences that had surfaced since the laws became operational, a goal that required the subcommittee to listen to the lived experiences of taxpayers, businesses, investors, and government agencies. This listening tour was institutionalised through the inclusion of over twenty representatives from government institutions, the private sector, and professional bodies on the committee, a deliberate effort to ensure that the recommendations would be both technically sound and administratively practicable. The Permanent Secretary of the Federal Ministry of Finance chaired the panel, while Albert Folorunsho, Chairman of the Tax Advisory Committee, served as co‑chair, lending the endeavour a blend of bureaucratic authority and private‑sector credibility.
Among the members were officials from the Nigeria Customs Service, the Nigeria Revenue Service, the Budget Office of the Federation, and the Legal Drafting Department of the Federal Ministry of Justice, alongside representatives from the Nigeria Economic Summit Group, the Institute of Chartered Accountants of Nigeria, the Association of National Accountants of Nigeria, the Chartered Institute of Taxation of Nigeria, the Nigerian Bar Association, and the Big Four accounting firms—Deloitte, EY, KPMG, and PwC—whose presence signalled a commitment to harnessing global best practices while grounding them in Nigerian realities. As Folorunsho pledged on behalf of the committee, the panel would engage relevant stakeholders before finalising its recommendations, a promise that underscored the minister’s insistence that every tax reform produces winners and losers, and that the ultimate measure of success lies not in popularity but in fairness, efficiency, and competitiveness. This human‑centred approach sought to temper the technocratic impulse with an awareness that complicated tax rules are themselves a tax, raising compliance costs and creating room for discretion, a insight that Oyedele had repeatedly emphasised when warning that the government must optimise the whole economy, not merely achieve a single revenue target.
The Digital Ledger: Technology, Coordination and the Path to 2027
Amid the debates over thresholds and transition rules, a quieter but potentially transformative current ran through the subcommittee’s deliberations: the call for greater digitalisation, data sharing, and coordination among revenue‑collecting agencies. The Leadership Newspaper noted that the government also wanted better coordination among revenue-collecting agencies and more effective use of digital systems and data sharing, a refrain that appeared repeatedly in the 134 submissions, which urged stronger measures against multiple taxation and improved coordination to prevent taxpayers from being repeatedly required to submit information already held by government agencies. This demand for streamlined processes was not merely a matter of administrative convenience; it carried profound implications for the investment climate, particularly in sectors such as mining, renewable energy, healthcare, and capital markets, where stakeholders had proposed measures to improve competitiveness through clearer tax regimes and faster refunds. The subcommittee’s mandate to review the Significant Economic Presence Order 2020 and work on an updated framework that aligned with the 2025 tax laws and international practices touched directly on this digital agenda, seeking to harmonise the taxation of digital enterprises with the broader reform while ensuring that the rules kept pace with evolving business models. Moreover, the committee’s broader scope—encompassing fiscal policy and management, public financial management, debt, transparency, capital markets, and cross‑border capital flows—reflected an recognition that tax policy cannot be viewed in isolation from the macro‑economic environment in which it operates.
By examining how tax administration intersects with debt management, for instance, the panel could identify opportunities to reduce borrowing costs through more efficient revenue collection, thereby addressing the concerns raised by civil society organisations that had protested the rising debt profile and demanded an end to excessive borrowing. The inclusion of the Debt Management Office and the Central Bank of Nigeria on the subcommittee ensured that these linkages would be explored with the rigor they deserved. As the six‑week deadline loomed, the panel’s work began to crystallise into a set of recommendations that would feed into the Finance Bill 2027, a legislative vehicle that Oyedele insisted should not be seen as merely another annual exercise but as a chance to preserve the fundamental principles of the 2025 reforms while learning from implementation and responding to new economic realities. In this way, the digital ledger of coordination and transparency promised to become a cornerstone of Nigeria’s next fiscal chapter, turning the promise of reform into a tangible tool for economic resilience.
Future Implications: A Blueprint or a Band‑Aid?
As the subcommittee’s six‑week window draws to a close, the nation watches with cautious optimism to see whether the forthcoming recommendations will constitute a durable blueprint for tax governance or merely a temporary band‑aid on persistent wounds. The stakes are high: Nigeria’s tax‑to‑GDP ratio remains stubbornly low compared with regional peers, and the ability to mobilise domestic resources is critical for financing the ambitious infrastructure agenda championed by President Tinubu, reducing reliance on volatile oil revenues, and creating fiscal space for social investments. If the panel succeeds in clarifying VAT thresholds, simplifying withholding tax procedures, resolving the Companies Income Tax transition dispute, and fostering seamless coordination among revenue agencies through upgraded digital platforms, the payoff could be a measurable uptick in compliance, a reduction in the cost of doing business, and a boost in investor confidence—particularly in the high‑growth sectors that stakeholders highlighted, such as renewable energy and healthcare. Conversely, if the recommendations merely tweak technical details without addressing the underlying culture of discretion and the perception of multiple taxation, the reform risk losing credibility, perpetuating the very ambiguities that have hampered corporate planning and eroded trust in the tax administration. The broader fiscal dimensions the subcommittee is tasked with examining—debt management, transparency, capital markets, and cross‑border flows—offer a lever to align tax reform with macro‑economic stability; for instance, improved revenue forecasting could lower borrowing costs, while transparent data sharing could curb illicit financial flows and enhance the country’s standing in international ratings.
Ultimately, the legacy of this review will hinge on whether it manages to balance the imperative of revenue mobilisation with the equally vital goal of creating a predictable, fair, and competitive tax environment that encourages entrepreneurship, protects low‑income households, and supports sustainable development. As Oyedele reminded his audience at the outset, every tax reform produces winners and losers, and the true test lies not in popularity but in whether the policy is fair, efficient, and competitive—a standard that the nation will be watching closely as the Finance Bill 2027 takes shape in the months ahead.
📰 Sources Cited
- Politics Nigeria: FG Begins Review of Implementation of 2025 Tax Reform Laws
- Leadership Newspaper: VAT, Withholding Tax, Capital Gains Top FG’s Tax Review Agenda
- Daily Trust: FG to review tax laws
- Punch Nigeria: FG begins six-week review of 2025 tax laws
- THISDAY: FG Sets up Technical Committee to Review 2025 Tax Acts
0 Comments
Sign in to commentNo comments yet. Be the first to share your thoughts!